

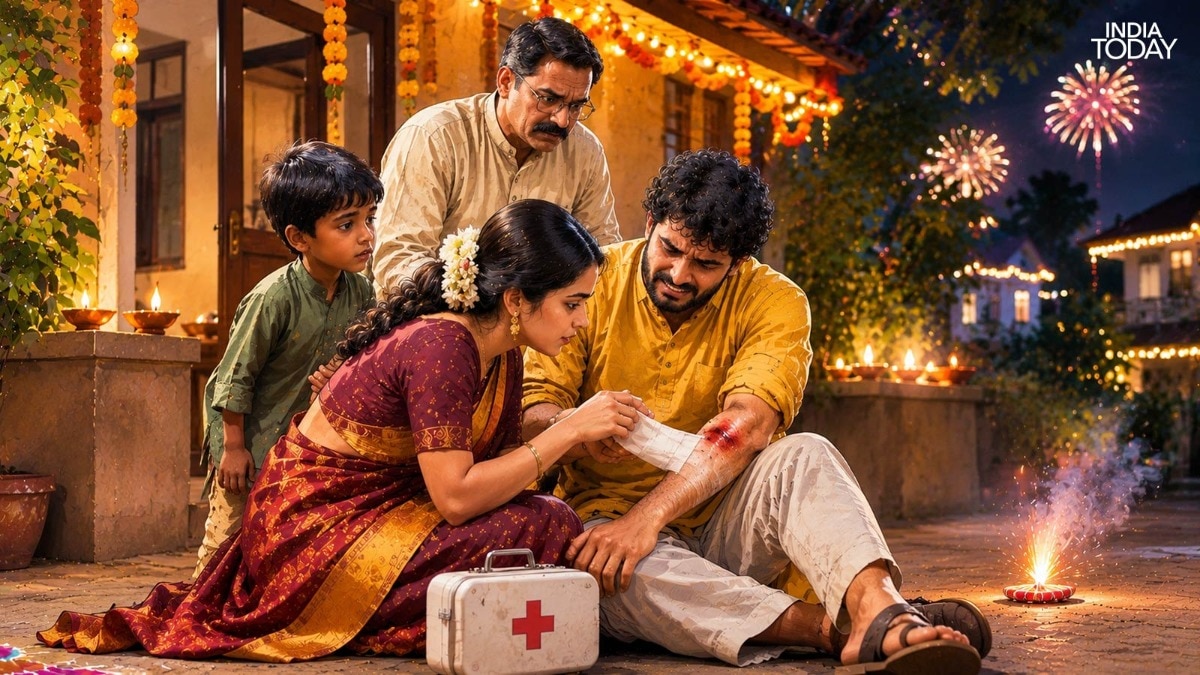
A Diwali celebration can go from festive to frightening in a matter of seconds. A firecracker that goes off in the wrong direction, a spark that catches on clothing or a stray rocket that sets something alight can leave families dealing with more than just a scare.
There could be hospital bills, surgery, weeks of follow-up treatment or even damage to the house.But will your insurance policy come to the rescue? While many people assume their health insurance will cover firecracker-related injuries, the answer is not always straightforward.
The type of policy you hold, the expenses involved and the circumstances of the accident can all determine how much protection you actually get.There are short-term firecracker insurance plans, regular health insurance and personal accident policies to consider. Home insurance can also help if a firecracker causes damage to your property.
However, each offers a different kind of protection, and simply having an insurance policy may not mean every expense is covered.Consumers have three broad options for protection against firecracker-related accidents: short-term firecracker plans, regular health insurance and personal accident insurance. Trupti Balasubramaniam, CEO and Principal Officer at Probus, says some insurers offer low-cost, short-term firecracker plans around Diwali.
These cover medical bills arising from firecracker accidents up to a specified limit."Your regular health insurance can also pay for treatment, and a personal accident policy can pay out for accidental death or permanent disability. Each covers something different, so check what yours includes," she says.
Shivendra Pancholi, Executive Director at Coverfox, says that there is no single, standardised policy that automatically covers every Diwali-related risk. Health insurance may take care of eligible hospitalisation and treatment costs, personal accident insurance offers defined benefits for accidental death or specified disabilities, while home insurance may cover fire-related damage to insured property.The right cover, therefore, depends on what you want protection against: medical expenses, loss of income due to disability or damage to your home.WILL HEALTH INSURANCE PAY FOR FIRECRACKER BURN INJURIES?A common assumption is that a regular health insurance policy will cover every expense if someone suffers burns while bursting crackers.
Most health policies do cover accidental burns, including those caused by firecrackers, but the extent of coverage depends on the policy terms.Pancholi says a health insurance policy may cover medically necessary hospitalisation, surgery, medicines, diagnostic tests and other eligible treatment expenses, subject to the sum insured and policy conditions.But the costs may not end when the patient leaves the hospital. Serious burns can require follow-up consultations, dressings, physiotherapy, reconstructive procedures and rehabilitation.
These expenses may be covered only if the policy provides for them."Burn injuries can require prolonged treatment, and the financial burden may extend well beyond the initial emergency visit," Pancholi says.Balasubramaniam adds that firecracker-specific plans usually cover hospitalisation and certain treatments up to a specified limit. A regular health policy generally covers hospital stays, surgery and prescribed medicines, but follow-up visits, dressings and rehabilitation may be restricted or capped."Most health policies treat firecracker burns like any other accidental injury.
But don't expect every rupee to be paid," she cautions.Consumers should check room-rent limits, co-payments, deductibles and treatment sub-limits. Outpatient treatment, in particular, may not be covered under many policies.
These conditions can make a significant difference to the amount an insurer eventually pays.WHAT IF A FIRECRACKER ACCIDENT CAUSES DISABILITY OR DEATH?The financial consequences of a serious firecracker accident can extend beyond medical bills. If an injury results in permanent disability or accidental death, a personal accident policy can provide an additional layer of protection.Health insurance primarily covers eligible medical expenses.
It does not ordinarily provide a lump-sum benefit to replace future earnings lost due to disability. A personal accident policy, on the other hand, may offer defined benefits for accidental death and specified disabilities.Balasubramaniam says that in the event of accidental death, the insurer generally pays the applicable sum insured to the nominee.
For permanent disability, the payout depends on its nature and extent, as well as the benefits specified in the policy.Pancholi advises consumers to check whether their policy covers permanent total disability, permanent partial disability and temporary disability. These are separate benefits and may not necessarily be included together.The payout is usually determined by the sum insured and the policy's benefit schedule.
Insurers may also ask for hospital records, medical assessments and a disability certificate before deciding the claim.IF SOMEONE ELSE BURSTS THE CRACKER, ARE YOU COVERED?You do not necessarily have to be the person handling a firecracker to suffer an injury. A bystander watching the celebrations or a family member standing nearby could also get hurt.So, does insurance cover such accidents?Balasubramaniam says an insured person may be able to claim even if they were only watching from a distance when the accident occurred.
However, the cover depends on whose name is on the policy.A spouse, child or parent will be covered only if they are included in the family floater or listed under the firecracker plan. A neighbour or guest standing nearby will not automatically be covered by someone else's policy.Pancholi says an injured bystander may be able to claim under their own health insurance or personal accident policy, provided the incident meets the policy terms.
The fact that the person was not handling the firecracker does not, by itself, guarantee that a claim will be accepted.The circumstances of the accident, the location and applicable exclusions may also matter. Consumers should therefore check exactly who is insured and what conditions apply.CAN AN INSURER REJECT A FIRECRACKER ACCIDENT CLAIM?A firecracker-related injury does not automatically guarantee an insurance payout.
The circumstances of the accident and the exclusions mentioned in the policy can influence the insurer's decision.Balasubramaniam says most policies exclude injuries arising from illegal activities, intentional self-harm or other specifically listed circumstances. If someone is injured while using banned firecrackers or ignoring basic safety instructions, the insurer may examine the claim more closely.That does not mean every such claim will automatically be rejected.
Much depends on the wording of the policy and the facts of the incident, she says.Pancholi also advises policyholders to review exclusions relating to unlawful activities, deliberate self-injury, intoxication or other specified circumstances, wherever applicable.If a claim is denied, consumers should ask the insurer for a written explanation that identifies the specific policy clause relied upon. They can then use the insurer's grievance-redressal process if they disagree with the decision.WHAT IF A FIRECRACKER DAMAGES YOUR HOME?The risk is not limited to physical injuries.
A stray rocket or spark could start a fire and damage a balcony, building, furniture or household belongings.This is where home insurance may help, but the extent of protection depends on what the policy covers.Balasubramaniam says home insurance generally covers damage to the building if a firecracker starts a fire. Furniture and personal belongings, however, are covered only if the policy includes contents cover.Pancholi says consumers should check whether their home insurance protects the structure, household contents or both.
These may be covered separately or under different limits.It is also important to distinguish between property and personal injury cover. Home insurance addresses damage to insured property, health insurance covers eligible medical expenses, while personal accident insurance may provide benefits for accidental death or disability.In other words, a home insurance policy should not be assumed to cover medical bills simply because the accident happened at home.HOW TO FILE A CLAIM AFTER A FIRECRACKER ACCIDENTIf an accident occurs, getting medical assistance and ensuring everyone's safety should come first.
Once the immediate emergency has been addressed, inform the insurer or its third-party administrator (TPA) as soon as possible and within the deadline specified in the policy.For a medical claim, consumers may need to submit the claim form, policy details, hospital admission and discharge papers, prescriptions, test reports, itemised bills and payment receipts. A medical certificate or disability assessment may also be required for a personal accident claim.For property damage, take photographs of the affected areas and keep repair estimates.
The insurer may also ask for proof of ownership, a loss assessment, a fire brigade report or an accident report, depending on the circumstances.Pancholi says policyholders should follow the insurer's cashless or reimbursement process and submit the required documents within the prescribed timelines. A police complaint is not necessarily mandatory for every medical claim, so consumers should check the requirements of their particular policy.WHAT SHOULD YOU CHECK BEFORE BUYING FIRECRACKER INSURANCE?There is no single minimum or maximum sum insured applicable to all firecracker insurance plans.
Special Diwali plans generally offer limited cover at relatively low premiums, while regular health and personal accident policies may provide higher sums insured. The limits for medical expenses, accidental death and disability can also vary.Both experts advise consumers not to be guided by the headline cover amount or the premium alone.Balasubramaniam says policyholders should read the policy document and Customer Information Sheet to confirm that firecracker-related injuries are covered.
They should also check who is insured, when the cover starts and ends, the exclusions and any waiting periods.Pancholi recommends checking the treatment limits, co-payments, deductibles, disability benefits and claim requirements. For home insurance, consumers should confirm whether the building, its contents or both are covered.A special firecracker plan can offer additional protection, but it should not be treated as a substitute for comprehensive health and personal accident insurance.The bottom line?
Before the Diwali celebrations begin, take a few minutes to check your insurance documents. A policy may offer a financial safety net, but knowing its limits is what tells you how much of the burden it will actually take off your shoulders.- Ends