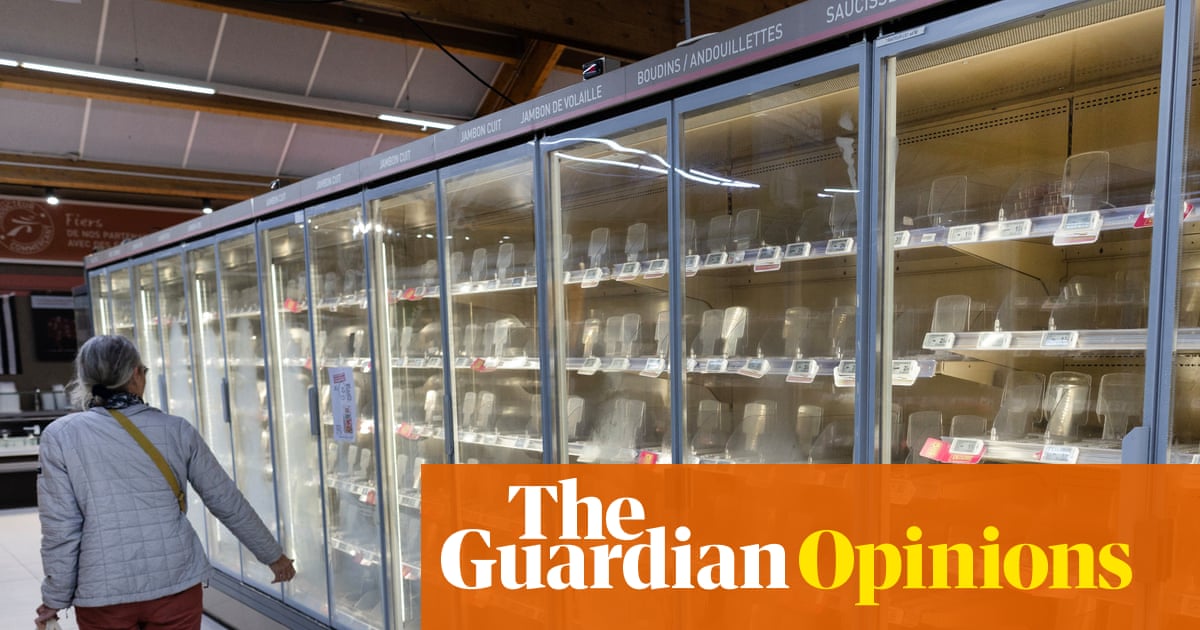


Unusual incidents involving compromised French refrigeration units provided an unexpected discussion point for international economists, central bankers, and financial leaders convening in Bangkok, highlighting the escalating expenses associated with cyber-attacks. International Monetary Fund managing director Kristalina Georgieva highlighted an event where French supermarkets discarded spoiled merchandise after hackers breached refrigeration controls and elevated temperatures to 50 degrees Celsius. Addressing the annual meetings in Thailand, she emphasized the necessity of defending against malicious actors within an interconnected environment, particularly as artificial intelligence amplifies digital fraud potential significantly. Authorities have previously cautioned that the intelligence boom might jeopardize financial stability through market corrections. Yet a distinct hazard emerged in Bangkok, with Georgieva expressing apprehension that AI-driven cybercrime could erode overall confidence in monetary systems. Social networking platforms frequently display fraudulent celebrity endorsements for cryptocurrency and gold, while traditional email schemes operate on a broader scale. Comparable to how low-quality digital content risks undermining factual journalism, Georgieva feared cyber-fraud might diminish consumer reliance on conventional banking institutions. Reflecting on her upbringing in Bulgaria behind the iron curtain, she noted that widespread distrust previously drove individuals to store currency in shoeboxes at home. She warned that failing to anticipate these trends could result in widespread withdrawal from formal banking networks. Similar concerns were echoed by JP Morgan chief executive Jamie Dimon, who stated the institution would restrict digital agents from acting on customer instructions due to the risk posed by thousands of autonomous entities. Meta platforms and comparable services are beginning to offer automated financial management tools that monitor savings rates and transfer funds automatically. Regulators harbor reservations regarding these developments, noting potential destabilizing effects during periods of uncertainty if funds move rapidly across the financial architecture. An additional dilemma involves accountability when automated financial actions produce negative or unlawful outcomes. Establishing legal precedence typically requires incidents to occur first, creating regulatory ambiguity that can accelerate financial instability, a dynamic observed during the 2008 crisis involving complex liability structures. Bank of England governor Andrew Bailey, heading the Financial Stability Board, referenced warnings from Anthropic indicating that artificial intelligence models might soon achieve self-replication within household hardware. Determining liability when internet-connected appliances malfunction remains an unresolved challenge. Potential consumer reactions might involve returning to standard non-connected hardware, mirroring actions taken by French supermarkets that disconnected refrigeration systems. Although rejecting smart appliances carries minimal societal detriment, the financial equivalent of returning to traditional methods would mirror Georgieva's shoebox scenario, carrying economic consequences. Bailey remarked that societal operations depend fundamentally on trust in currency. Senior financial authorities remain deeply concerned by the convergence of advanced artificial intelligence and global financial networks encompassing social platforms and payment applications. This development coincides with governance in the United States, the center of the intelligence boom, where leadership has focused on alternative naming conventions rather than regulatory debate.
Cyber-Threats and Artificial Intelligence: Global Financial Stability at Risk
Economic leaders gathered in Bangkok warn that artificial intelligence is supercharging cybercrime and digital fraud, threatening consumer trust in the global financial system and creating severe regulatory challenges.